Budget 2027: What Malaysian first-home buyers should know

Budget 2027 proposes two forms of help for first-time buyers: reduced stamp duty on the purchase and financing assistance. These can lower upfront costs or help some buyers access a loan, but neither makes a home automatically affordable.
Stamp duty: proposed relief
For sale and purchase agreements (SPAs) executed from 1 January 2027 to 31 December 2030, the Budget proposes full stamp duty exemption on the transfer instrument and loan agreement for a qualifying first home priced up to RM500,000. For a first home priced above RM500,000 and up to RM750,000, the first RM500,000 would be fully exempt and the remaining portion would get a 50% exemption. The Ministry of Finance’s tax-measures document sets out these proposed thresholds and dates.
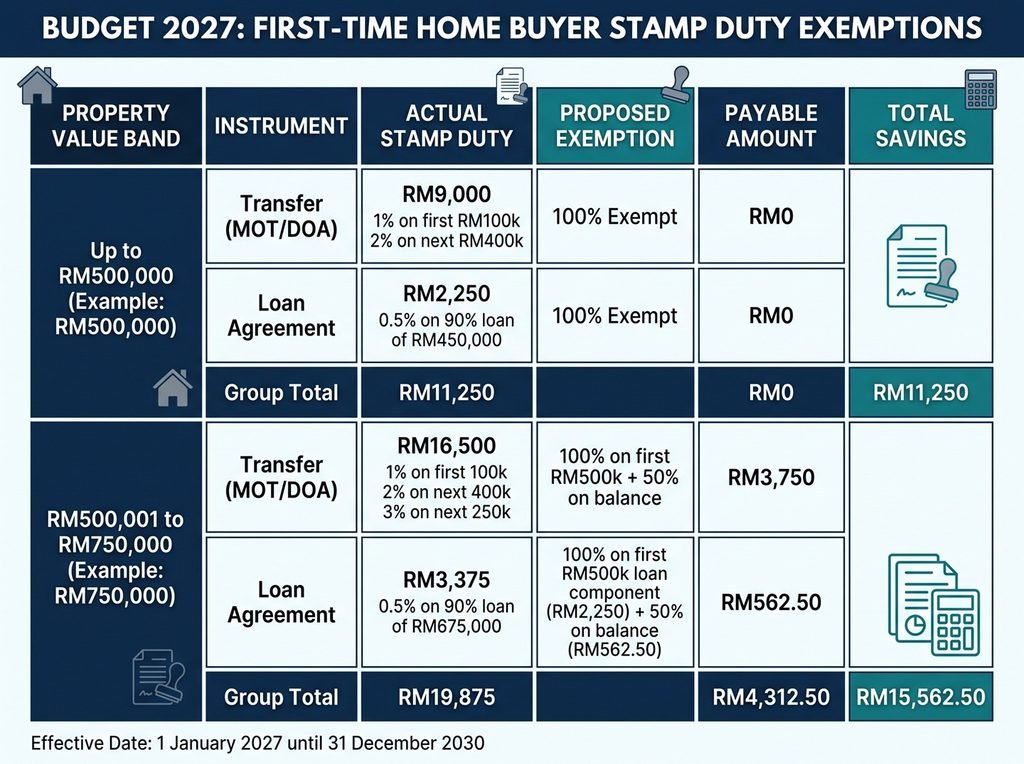
In plain terms, the relief applies to two important documents: the transfer of ownership (MOT) and the stamp duty on loan agreement. It does not mean every purchase cost disappears. Buyers should still budget for items such as their deposit, legal fees, valuation, insurance or takaful, and ongoing maintenance where applicable.
SJKP: help with financing
Budget 2027 provides for up to RM20 billion in housing-financing guarantees through Syarikat Jaminan Kredit Perumahan (SJKP), with the stated aim of assisting 80,000 first-time buyers, particularly self-employed people and those without fixed incomes. A guarantee is not a cash grant or an automatic loan approval: buyers still apply through participating financial institutions (banks), which assess repayment ability and set the financing terms.
SJKP’s existing Madani scheme describes financing of up to 120% of the home’s purchase price, with the extra portion potentially covering specified costs such as legal fees, renovation and furnishings. Actual limits and conditions depend on the scheme and participating lender, so confirm the current offer directly before relying on it.
This may be relevant to a gig worker or small trader who can show a reliable income history but does not have conventional monthly payslips. It may widen the route to an application; it does not remove the need to show that instalments are manageable.
The trade-offs buyers should weigh
Stamp-duty relief can reduce transaction costs, while a financing guarantee may help some eligible buyers access a loan. Neither reduces the purchase price itself, guarantees that a bank will lend, or makes monthly repayments lower by itself. Borrowing more to cover costs can also mean a larger debt and higher repayments over time.
The incentives are aimed at first-home purchases, not property investors buying an additional unit. The Budget’s official tax appendix describes the proposed relief as applying to the first residential home of Malaysian citizens. As the detailed rules and implementation matter, ask your conveyancing lawyer or lender to confirm eligibility against your circumstances and the documents before committing.
The Budget also proposes full stamp-duty exemption for specified transfer and loan instruments connected with the revival of abandoned housing projects, covering rescue developers or contractors and original buyers. This is a separate measure, not a general discount for anyone buying a resale home.
Practical takeaway
If you are planning a first purchase, compare the full cash needed at completion and the monthly repayment—not just the advertised price or possible duty saving. Check whether your SPA date falls within the proposed relief period, ask your lawyer to confirm eligibility, and ask your lender whether SJKP applies to you and the property.
Hafiz Noor