Refinance
Thinking of Refinancing Your Home?
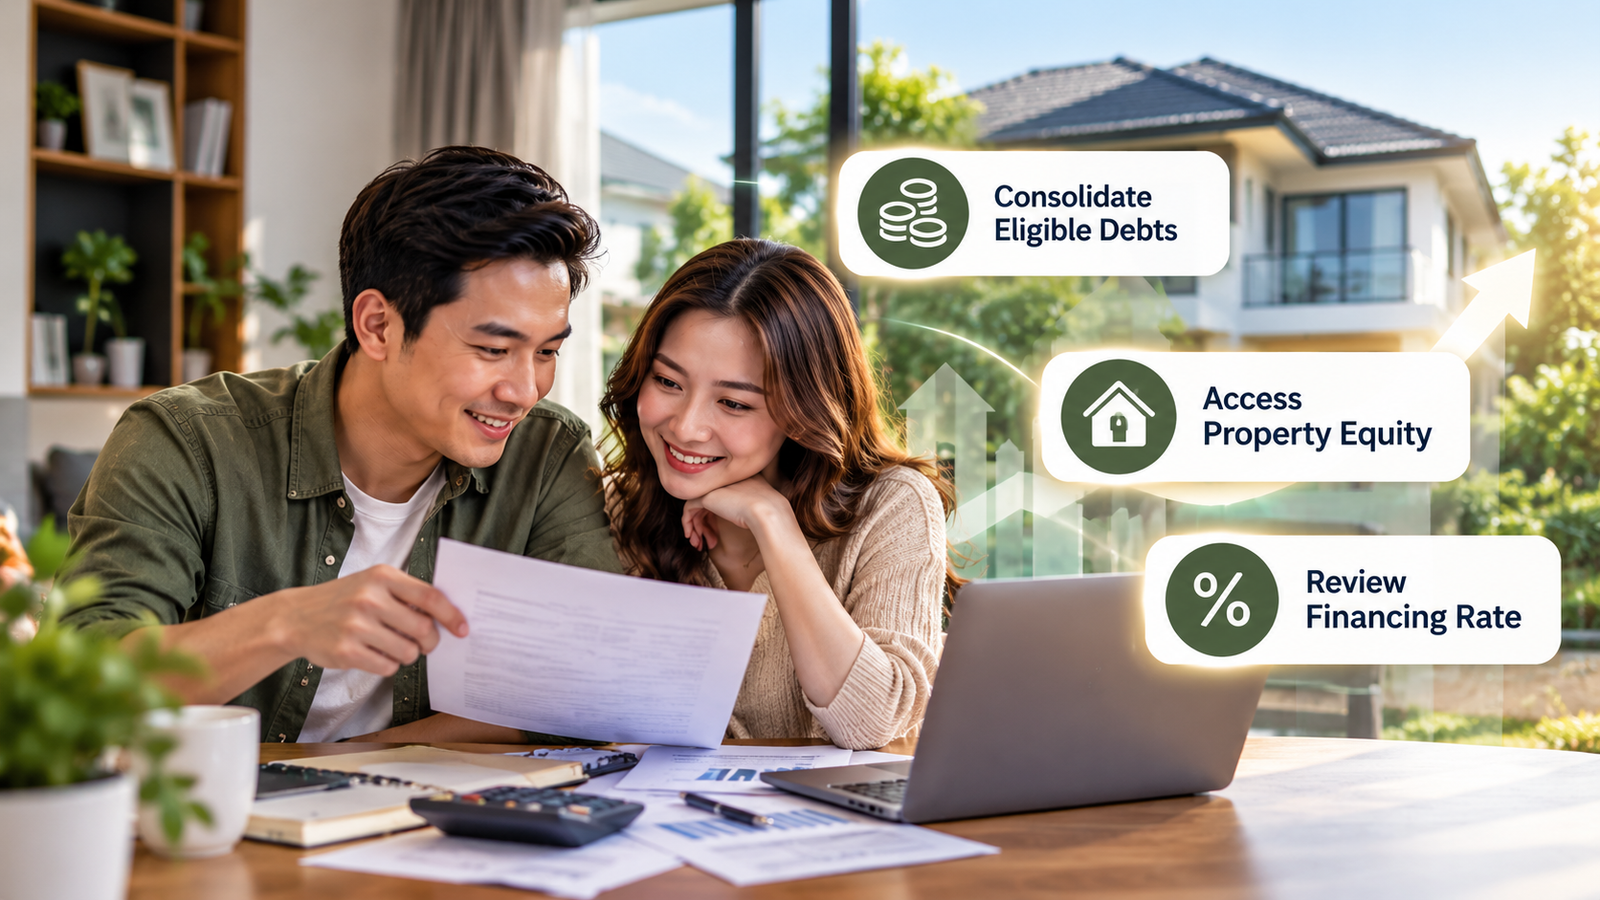
Your property value may have increased over the years. Depending on your outstanding loan and eligibility, refinancing could give you more options — from consolidating eligible debts to accessing property equity or reviewing your financing rate.
*HN Property is an enquiry platform, not a bank. Applications are assessed by relevant providers.
Why Consider Refinancing Your Home?
Property values may have increased since you first bought your home. If your property has built up equity, it may be worth reviewing your options.
Depending on your situation, refinancing could help you settle eligible debts, access some of your available property equity or review your current financing terms.
But don't look at the monthly instalment alone. Compare the total costs, remaining tenure and overall amount you may pay before deciding.
What Could Refinancing Help You Do?
Manage Multiple Debts
Juggling credit cards and personal loans every month? Depending on lender criteria, refinancing may let you settle eligible debts through one new financing facility. This could simplify your monthly commitments, but compare the total cost before deciding.
Explore Your Property Equity
If your property has sufficient equity, you may be able to access part of that value through cash-out refinancing. The amount depends on valuation, your outstanding loan, financing limits and approval.
Review Your Financing Rate
Your current financing may no longer be the best fit. Compare available rates, tenure and total costs to see whether another facility could suit your current financial situation.
Refinancing Estimate Calculator
Compare your existing commitments with potential new terms. See estimated changes to monthly payments and total financing required.
1 Existing Home Financing
RM
RM
% p.a.
Years
2 Other Debts to Consolidate (Optional)
Add personal loans, credit cards, or car loans you wish to settle using the new financing.
3 Proposed New Home Refinancing
% p.a.
Years
RM
Adjust this to estimate how much may remain after settling your home balance and selected debts. Actual fees and charges are not included.
Estimated Results
Financing Breakdown
Proposed Financing Amount
RM 0
Less: Existing Home Balance
- RM 0
Less: Debts Covered
- RM 0
Debt Shortfall
RM 0
Proposed amount cannot settle all selected debts.
Est. Remaining Cash-Out
RM 0
Monthly Commitments
Current Home Instalment
RM 0
Current Debt Payments
RM 0
Est. Current Total
RM 0
Est. Proposed Total
RM 0
(New Home Instalment only)
Est. Monthly Cash Flow Change
RM 0
Difference
Est. Total Repayment (Current)
RM 0
Est. Total Repayment (Proposed)
RM 0
Est. Total Interest/Profit Diff.
RM 0
A lower monthly payment may result from a longer tenure, which often means paying more total interest/profit over time.
Disclaimer: This calculator provides illustrative estimates based on standard amortisation formulas. It does not constitute a financing offer, confirmation of eligibility, or guarantee of savings. Actual rates, fees, and approval are subject to individual lender assessment. Ensure you compare the total cost of financing, not just monthly instalments. If proposed financing does not cover all debts, you remain responsible for the unpaid balances.
How Does Cash-Out Refinancing Work?
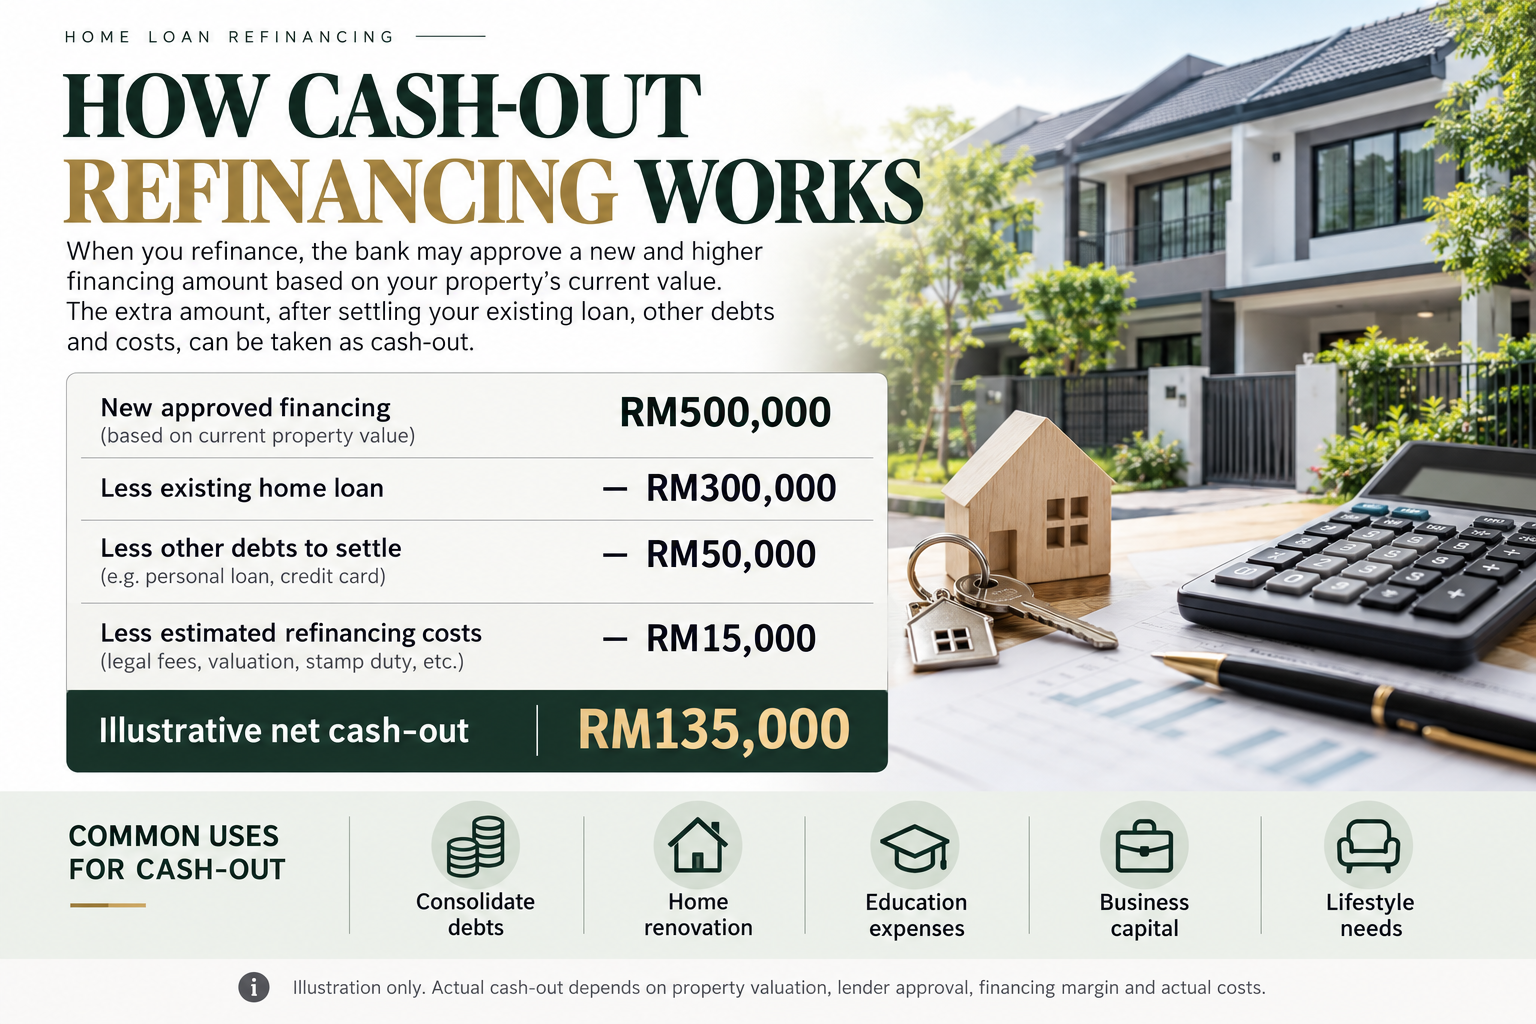
Let's say your bank approves RM500,000 in new financing. After settling your existing home loan of RM300,000, other eligible debts of RM50,000 and estimated refinancing costs of RM15,000, you could have around RM135,000 in potential cash-out.
Instead of juggling separate repayments for your home loan, personal loans and credit cards, refinancing may allow you to settle eligible debts through one new housing financing facility. This could make your monthly commitments easier to manage and improve your cash flow, especially if the new financing rate is lower than the rates on your existing debts.
For context, personal loan rates can be around 8–12%, while credit card interest can reach 18% per year. Housing financing rates may be lower, but the actual rate depends on the lender and your circumstances.
Do remember: a lower monthly instalment does not automatically mean you pay less overall. A longer financing tenure may increase your total interest or profit paid. Compare the monthly repayment, total financing cost and all applicable fees before deciding.
Illustration only. Actual cash-out depends on property valuation, outstanding financing, eligible debts, lender approval and actual costs.
How the Refinancing Process Works
1. Submit Your Documents
Share the required property, income and existing financing documents for an initial review.
2. Bank Assessment
The bank assesses your application, property valuation, eligibility and proposed financing terms.
3. Existing Loan Settlement
If approved, the refinancing proceeds through the relevant legal and settlement arrangements. Any eligible debts included in the approved facility are settled according to the agreed arrangements.
When Is Refinancing Worth Considering?
Worth Reviewing If
- Your current financing rate is noticeably higher than comparable available offers.
- You have available property equity and a clear purpose for accessing it.
- You are managing multiple eligible debts and want to explore consolidating them through refinancing.
May Be Less Suitable If
- You are still within a lock-in period and early-settlement penalties may apply.
- Legal fees, valuation fees, stamp duty and other upfront costs outweigh the potential benefits.
- You plan to sell the property in the near future.
Whether refinancing makes sense depends on your own numbers. Compare the total cost and remaining tenure before making a decision.
See How Debt Consolidation Through Refinancing Works
Multiple monthly commitments? Watch how property refinancing may help eligible homeowners explore debt consolidation, property-equity cash-out and financing-rate options.
About HN Property
HN Property is a Malaysian property information and enquiry platform. We help homeowners understand their options and connect them with relevant property and financing insights.
*Please note: HN Property is not a bank or direct lender. Any financing terms are subject to formal assessment by regulated financial institutions.
Further Reading
Debt Consolidation with House Refinancing in Malaysia
Understand how property refinancing may help eligible homeowners manage selected existing debts and what to consider before applying.
Why Debt Service Ratio (DSR) Matters for Your Home Loan Approval
Learn how lenders assess your existing financial commitments when reviewing a home financing application.
Frequently Asked Questions
Explore Your Refinancing Options
Tell us what you hope to achieve — whether it's debt consolidation, accessing property equity or reviewing your current financing. We can help you understand the next steps and information needed for an initial review.