Subsale Property Purchase Process in Malaysia: A Step-by-Step Guide

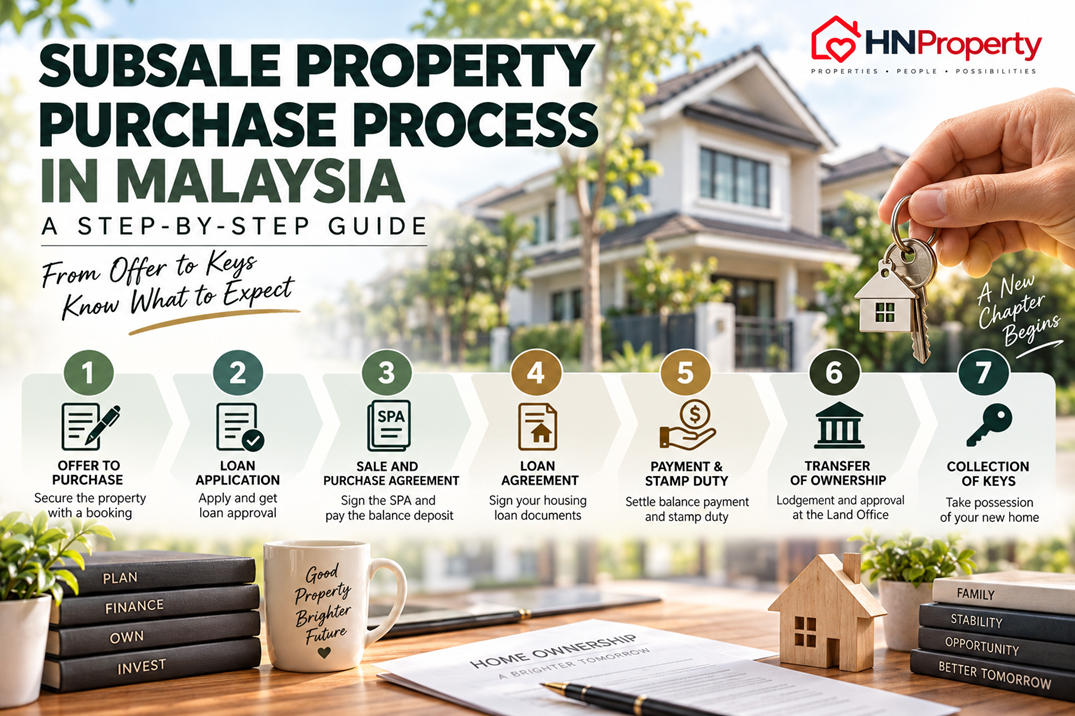
You’ve found your Dream Home, not by visiting a show unit from a Developer, but a completed unit in a matured or establish township. Now you’re keen to proceed but not sure on what is the next process? No worries, this article will serve as a step-by-step guide on purchasing a property from the Subsale/ Secondary market.
- Offer to Purchase and Booking
You’ve agreed on the property price with the Vendor and before you proceed with placing a booking of around 2% – 3% of the property price and signing the Offer to Purchase (OTP)/ Letter of Offer. You should know that normally, the OTP will state the basic terms, including:
- Purchase price
- Earnest or booking deposit
- Deadline for signing the SPA
- Vacant possession terms
- Other conditions agreed between buyer and seller
During this period, you will submit for your loan/ financing application. However take note that the Bank will appoint their valuer to value the property, and if the value of the property is lower than the purchase price. Any difference from loan approval against the selling price is payable by you the as purchaser.
- Most realtors will check the property value prior to accepting the earnest deposit from purchaser.
- Appoint Your Conveyancing Lawyer
Among other things, your lawyers job is not just to prepare the SPA, but also:-
- Prepare/ reviewing the SPA
- Conduct Land/ Title search
- Coordinate with Vendors lawyer, Bank and Authorities (LHDN, Land Office etc)
- Prepare transfer documents (MOT)
- Monitor Vacant Possession
- Sign the Sale and Purchase Agreement (SPA)
The buyer and seller will then sign the Sale and Purchase Agreement (SPA). This is the main contract governing the sale. During this period you will also be required to sign the transfer of property (Form 14A) and pay the differential sum which will be indicated in the schedule of the SPA.
For example:
| Payment | Example |
|---|---|
| Purchase price | RM700,000 |
| Booking deposit (3%) | RM21,000 |
| Loan Amount | RM630,000 |
| Balance deposit on SPA | RM49,000 |
| Total deposit | RM70,000 / 10% |
- Loan Agreement and Financing Documents
Ideally you would have sign your Bank Letter Offer based on your approved loan prior to signing the SPA. Thus the loan agreement is an agreement between you (purchaser) and the Bank (Financier). The Bank’s security will register a charge over the property with an issued/ individual title, however if theres no individual/ strata title, the bank financing structure may involve and assignment on the purchasers right of the property.
- Stamping and Stamp Duty
The ad valorem stamp duty on the property transfer is tiered, based on the property price:
| Property value | Stamp duty |
|---|---|
| First RM100,000 | 1% |
| Next RM400,000 | 2% |
| Next RM500,000 | 3% |
| Above RM1 million | 4% |
Do take note that the duty is generally calculated by reference to the Sale Price or Market Value, whichever is applicable/higher under the Stamp Act.
For example, assuming a property value of RM800,000:
- First RM100,000 × 1% = RM1,000
- Next RM400,000 × 2% = RM8,000
- Remaining RM200,000 × 3% = RM6,000
Estimated transfer stamp duty = RM15,000
- Redemption of Sellers Existing Loan
This happens behind the scenes in many subsale transactions. Suppose the seller still owes their bank RM300,000 and you are buying the property for RM700,000. Part of the purchase money will be used to redeem the seller’s outstanding loan so that the Seller Bank may discharge the title before your lawyer can register the title to your name and charge against the Bank, prior to the Bank disburse the balance of the purchase price to the Seller (Vendor).
- Completion and Vacant Possession
The transaction is complete once the purchase price has been fully paid in accordance with the SPA. The seller then hands over the property according to the SPA.
For a normal subsale house, this usually means:
- Keys
- Access cards
- Car park access/stickers
- Relevant remotes
- Vacant possession
With that in mind, before you proceed with the next step, it is advisable to seek a trustworthy and reliable solicitor/ lawyer to assist in protecting your interest in the purchase of your Dream Home.
Hafiz Noor